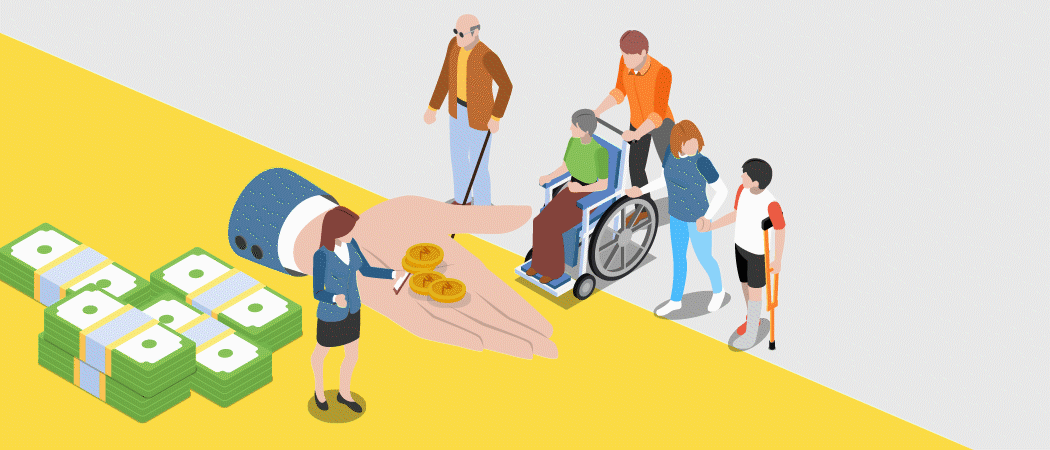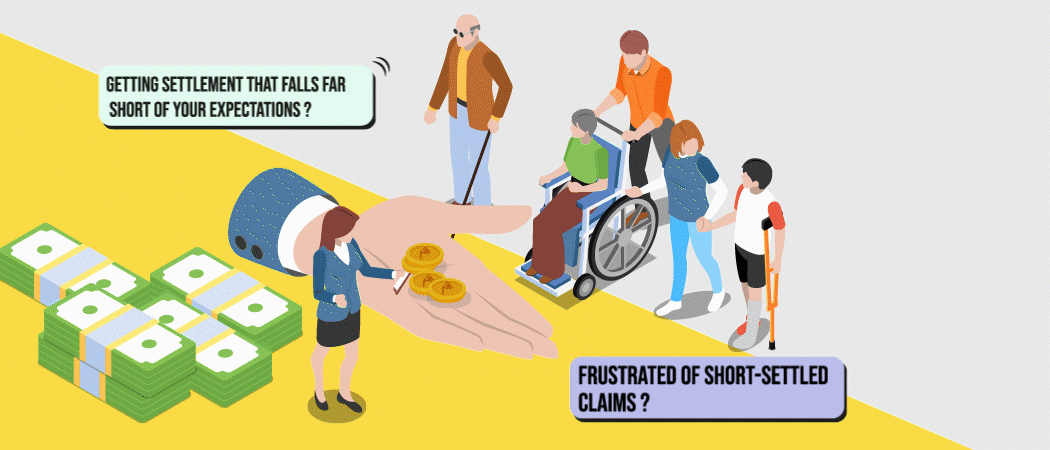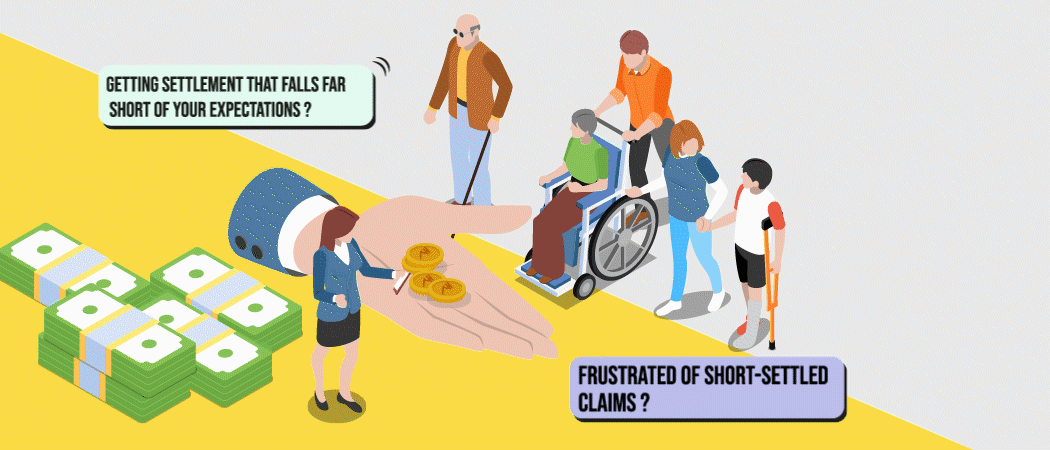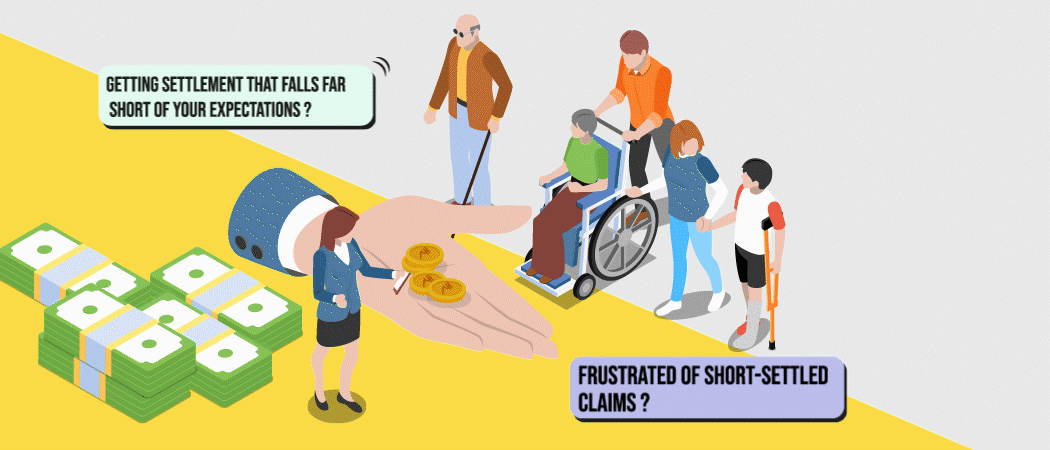
Your hospital bill was ₹3,20,000. The insurer paid ₹1,10,000. The TPA cites “reasonable and customary” caps, “non-payable items”, and a hundred small deductions. Each one is contestable.
"Reasonable & Customary" Often Means "Whatever We Decide"
Short-settlement is the most common — and least challenged — form of claim abuse in India. The denial letter is split into a thousand small reductions: room-rent caps, “non-payable items”, proportionate deductions, customary-charge caps. Individually each looks small; together they can halve your settlement. The IRDAI has specific guidelines on each of these reductions, and most insurers ignore them.
Our Approach
A Forensic Line-Item Audit of the Settlement Letter
We take the settlement statement and audit every reduction against (a) your policy wording, (b) IRDAI norms, (c) PMR / CGHS reference rates, and (d) hospital tariff documents. Where reductions are unjustified, we file a structured supplementary claim demanding the differential — usually with a 60-70% recovery rate.
What You Get
Concrete Outcomes, Not Empty Promises
Line-Item Audit
A forensic review of every deduction in the settlement statement against your policy and IRDAI guidelines.
Differential Recovery
Supplementary claim filed for the wrongly-deducted amount, usually 30-60% of the original short-settlement.
Room-Rent Cap Reversal
Where the proportionate deduction has been mis-applied (a very common error), we challenge and reverse it.
Future Claim Protection
A clear schedule of what is and isn't payable on your policy, so the next claim isn't short-settled.
Our Process for This Service
A Methodical, Documented, Fully-Accountable Workflow
01 · Send Us the Settlement Letter
Share the settlement statement, hospital final bill, and your policy document. We audit within 72 hours.
02 · Identify the Recoverable Differential
We mark each reduction as justified, partially justified or fully challengeable.
03 · File Supplementary Claim
A structured letter to the insurer's Grievance Officer with citations from IRDAI circulars and your policy wording.
04 · Recovery
The differential amount is credited. Our fee is a percentage of the additional recovery only — never of the original settlement.
No. It applies only when you opted for a higher room category than your policy permits, and even then it must be proportionate. We have reversed hundreds of mis-applied proportionate deductions.